Private markets explainers
140 short videos on the terms of private markets, with the words written out. What a term means and why it matters to investors.
Prefer to read? The glossary has every term in words.
Private equity
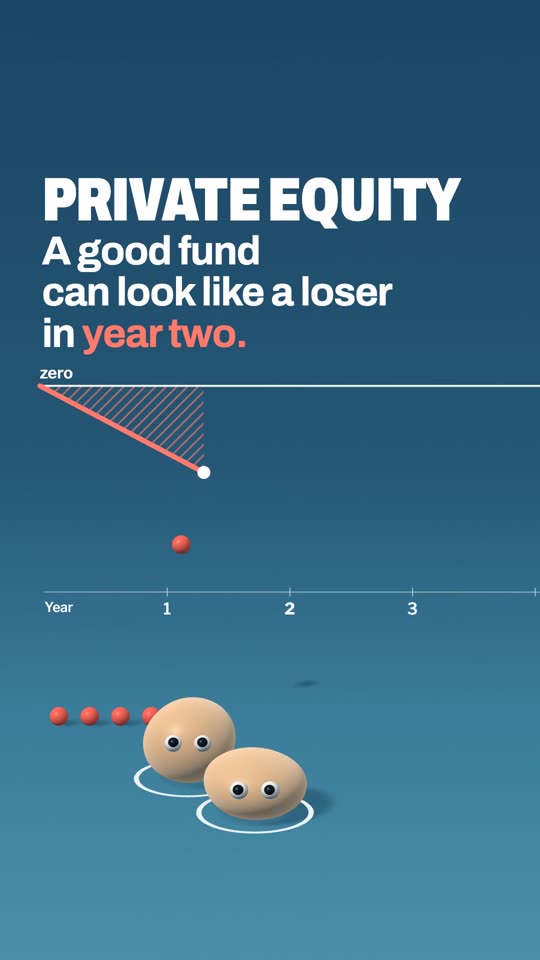 Why good funds look bad in year two17 seconds
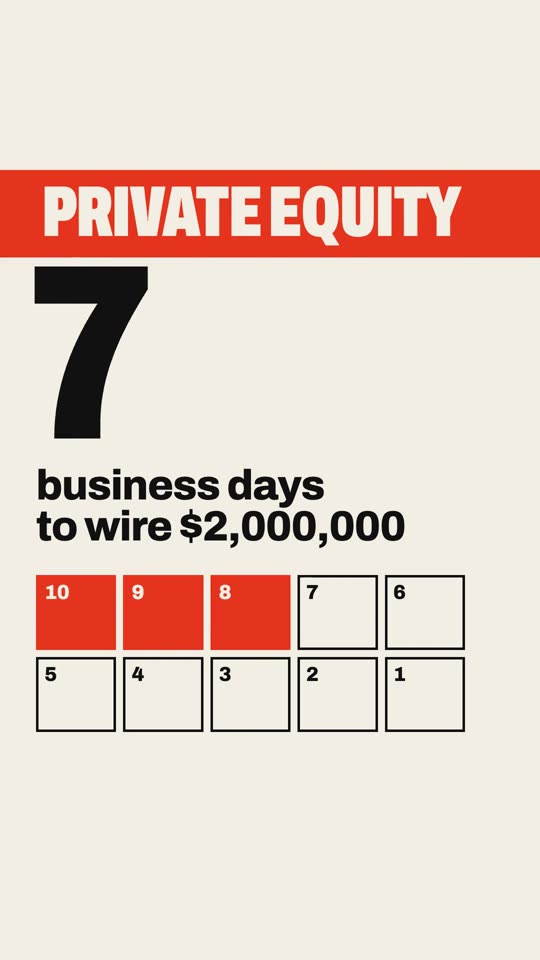 10 business days to wire $2M: the capital call16 seconds
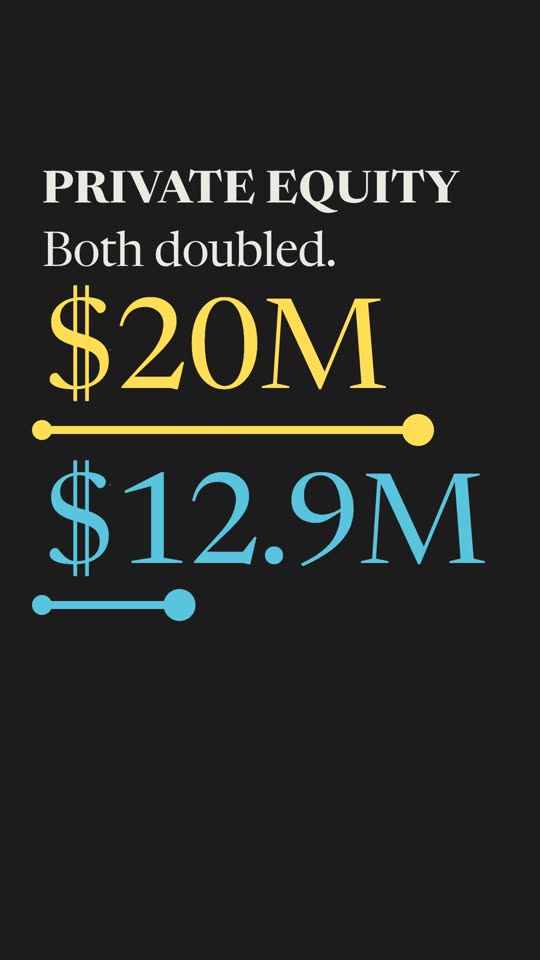 Both doubled your money. One was far better.20 seconds
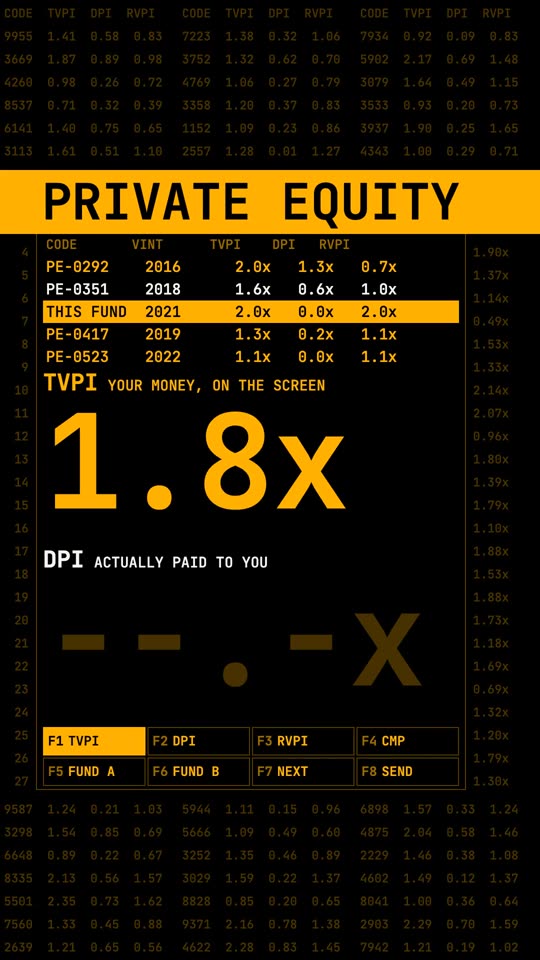 You can't spend TVPI24 seconds
 Same fund, different deal: the side letter21 seconds
 The manager sold the company. To itself.25 seconds
 Dry powder isn't sitting in a bank20 seconds
 An 8% preferred return is not a guarantee22 seconds
 Took $10M, earned $4M: the clawback41 seconds
 How a fund borrows against what it owns: the NAV loan25 seconds
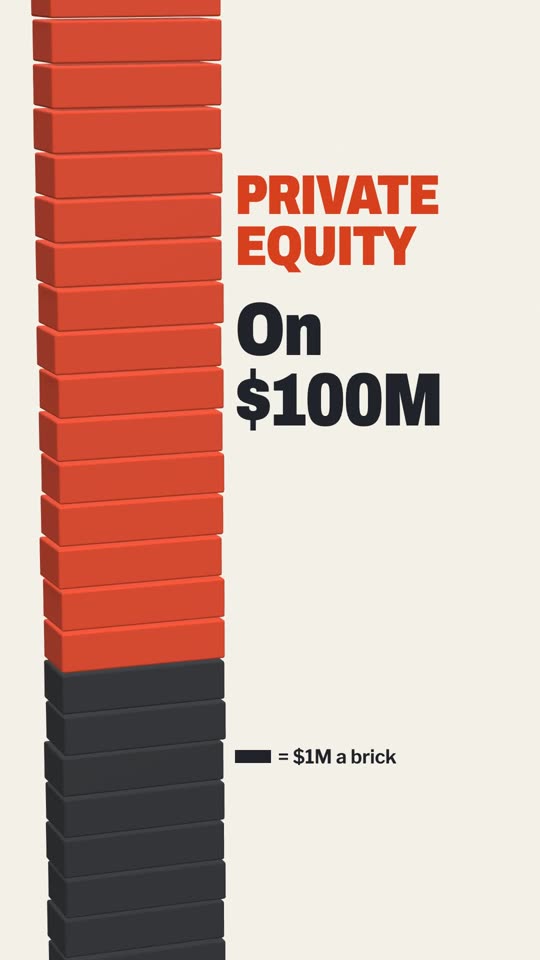 What 2 and 20 can cost on $100M22 seconds
 One person quits and the fund can stop buying24 seconds
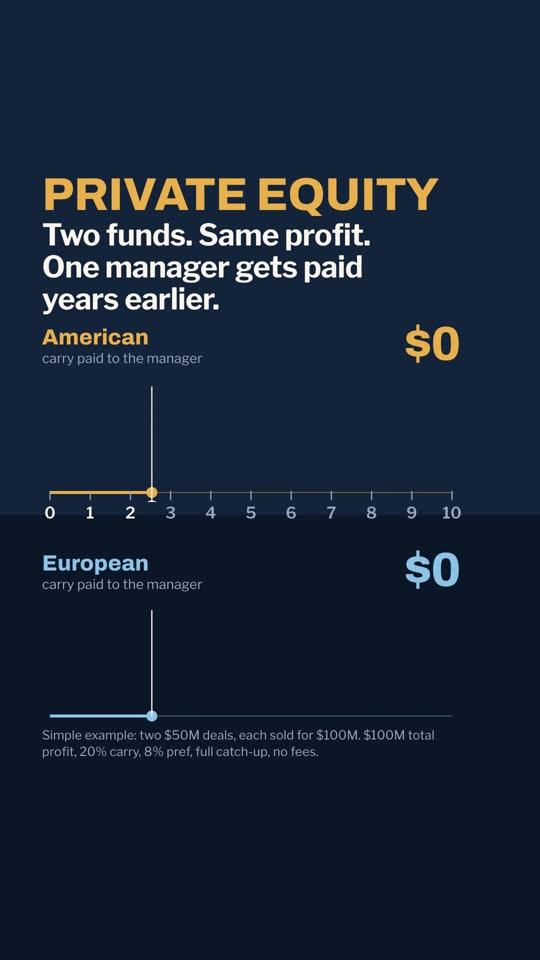 Same profit. One manager gets paid years earlier.26 seconds
 When the manager has to give money back22 seconds
 Why a fund's birth year changes how good its returns look30 seconds
 Opposite sides of the world, the exact same deals30 seconds
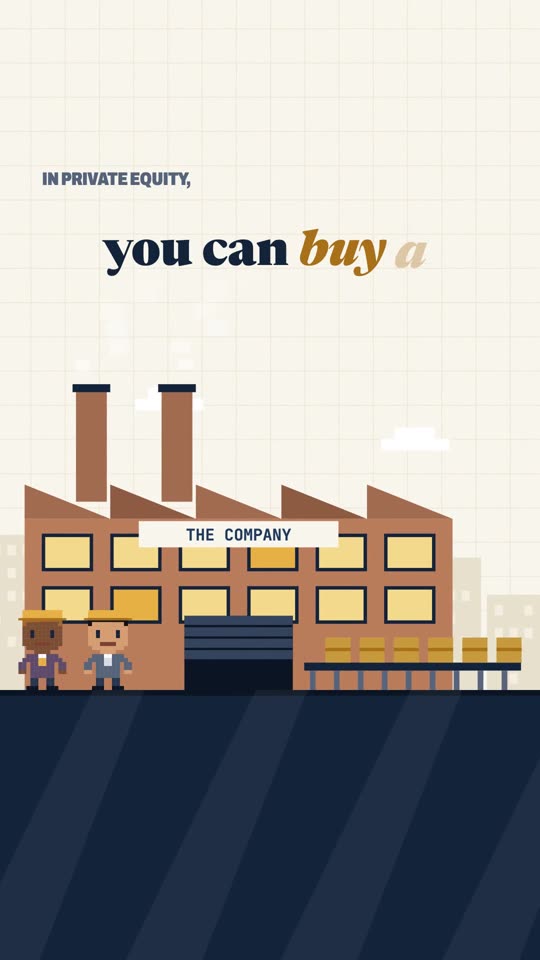 Buy a company, then hand it the loan46 seconds
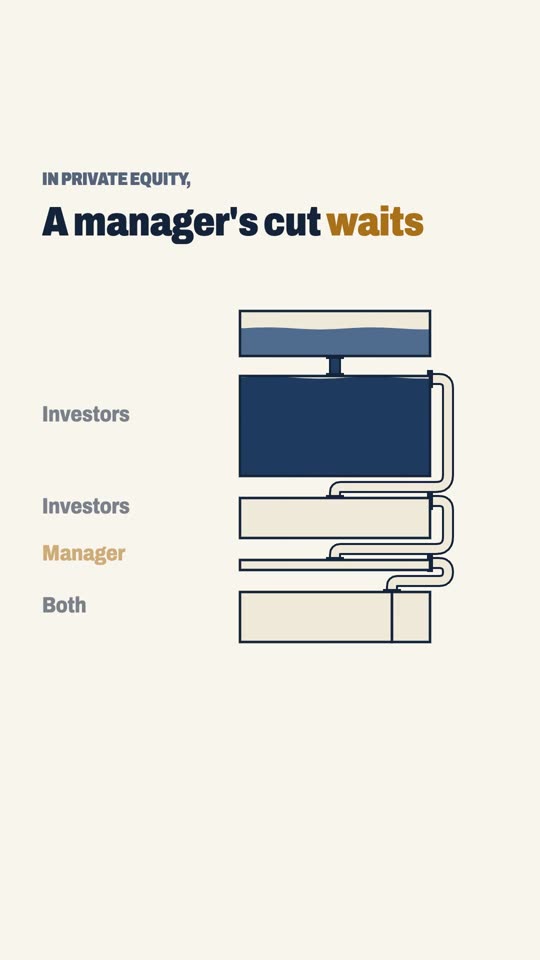 A manager's cut usually waits behind the investors47 seconds
 Investors can fire the manager and never say why34 seconds
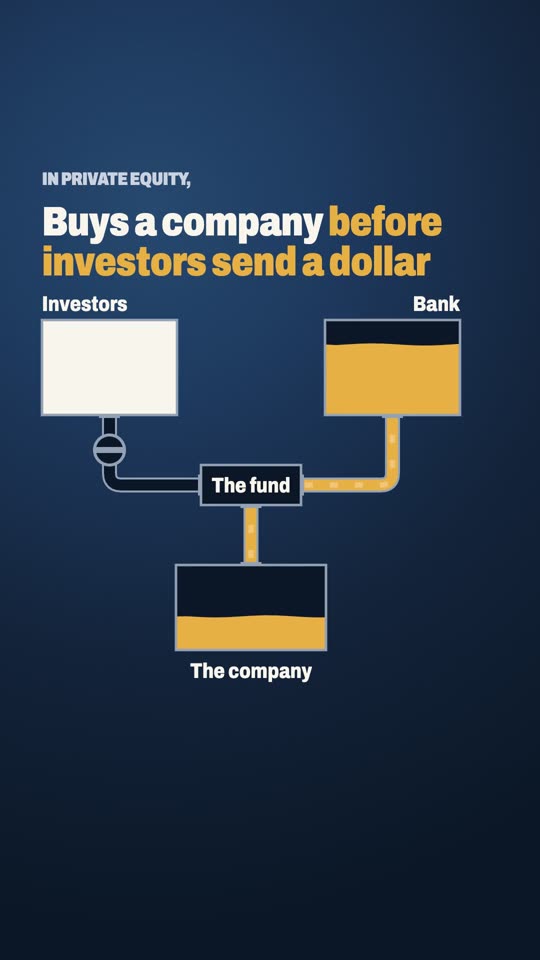 A fund can buy a company before investors send a dollar52 seconds
 One continent. Many doors. How funds get sold in Europe.39 seconds
 A company sells one wing. Then the wires get cut.35 seconds
 Six letters can set the price of a company35 seconds
 One deal, split across an ocean: the parallel fund38 seconds
 Same profit. A hundred million more.39 seconds
 Five small companies, bought cheap. One big one, sold dear.38 seconds
 Three rival firms, one company31 seconds
 A smaller investor can claim a bigger investor's discount33 seconds
 Buy one company. Bolt on ten more.36 seconds
 Some funds can't take your money unless you pass a test34 seconds
 You can buy a piece of the manager itself31 seconds
 Some investors put a company between them and the fund32 seconds
 85 of 100 investors came back. That says a lot.32 seconds
 A fund shows a gain. Most of it is not cash yet.30 seconds
 One private equity firm sells a company to another33 seconds
 The manager's real payday isn't the fee36 seconds
 Every fund has two sides. Only one picks the deals.33 seconds
 A billion dollar price tag, and only $700M is for the shares31 seconds
 A private fund with no end date30 seconds
 The people running a company can buy it32 seconds
 One deal can get a company all its own32 seconds
 A fund's size isn't known until the door shuts34 seconds
 Most private funds can't advertise. Some can, with a catch.34 seconds
 A fund can be told to stop buying, halfway through its life31 seconds
 A pension can end up with too much private equity without buying any35 seconds
 You can’t buy private equity in a day38 seconds
 A big investor can have a fund all to itself32 seconds
 A buyer can knock millions off the price before signing34 seconds
 Some funds take only investors well above accredited39 seconds
 A fund’s return means little until you compare it to the market32 seconds
 A fund investor can owe tax on money it never received36 seconds
 The same valuation can mean two different deals32 seconds
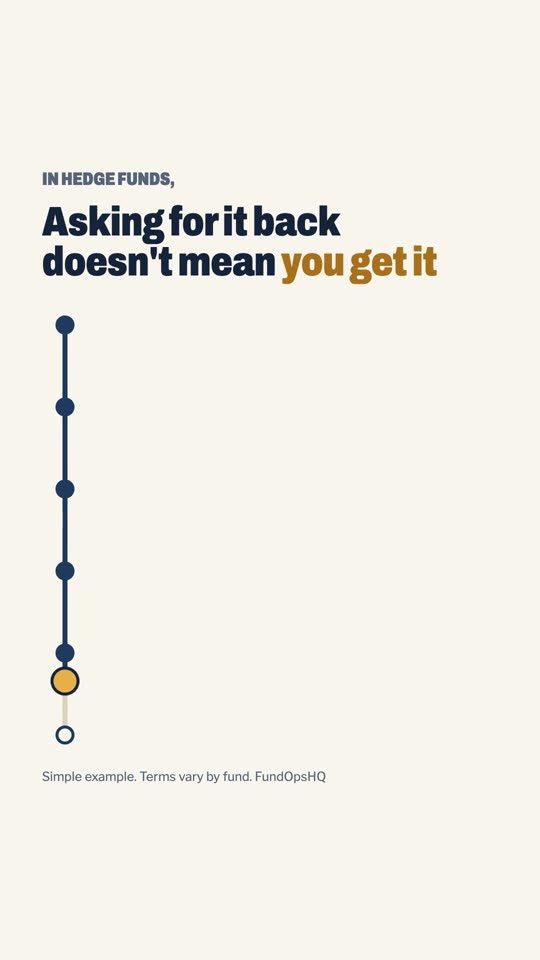 Asking for your money back doesn't mean you get it32 seconds
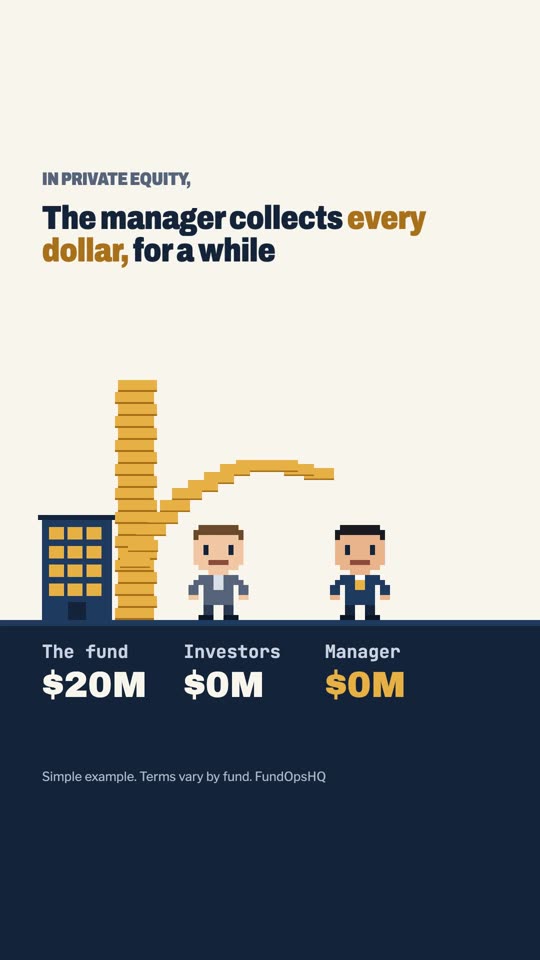 The stretch where the manager gets every dollar36 seconds
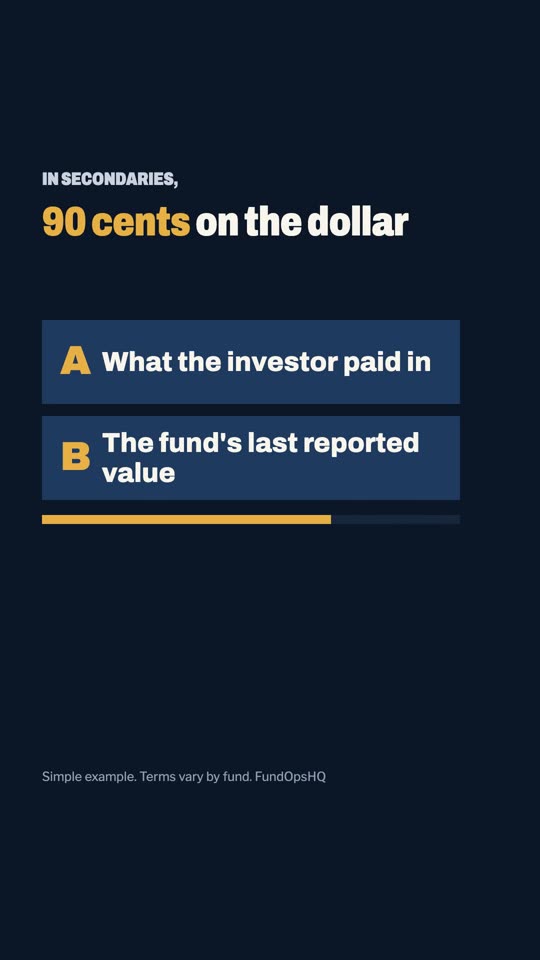 90 cents on the dollar. 90 cents of what?27 seconds
 One loan doing the job of two: the unitranche22 seconds
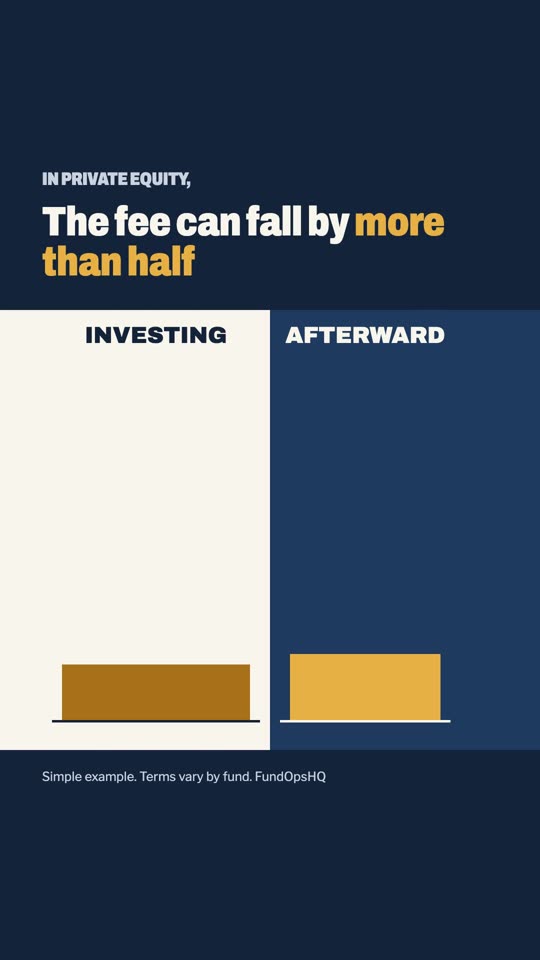 The same fund, and the fee falls by half26 seconds
 A fund can start investing before it finishes raising25 seconds
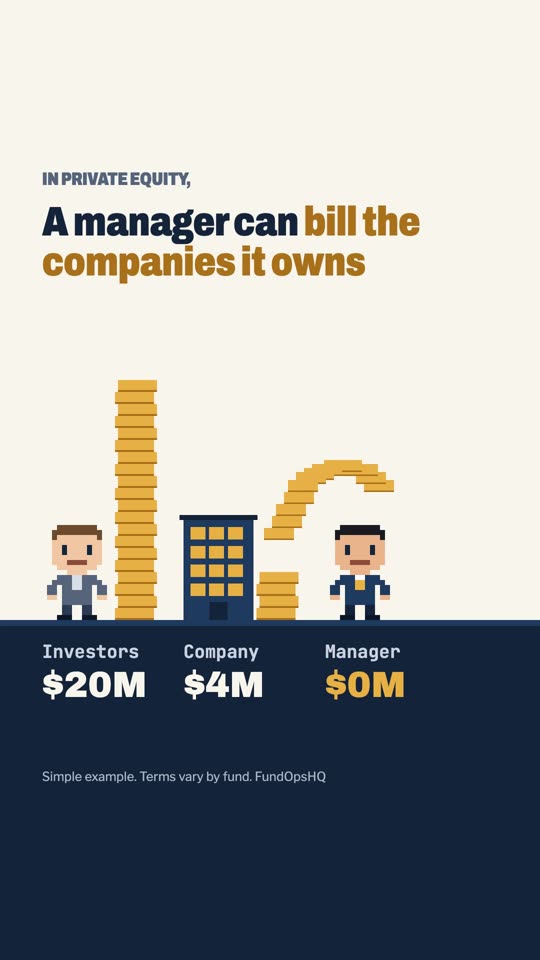 A manager can bill the companies it owns26 seconds
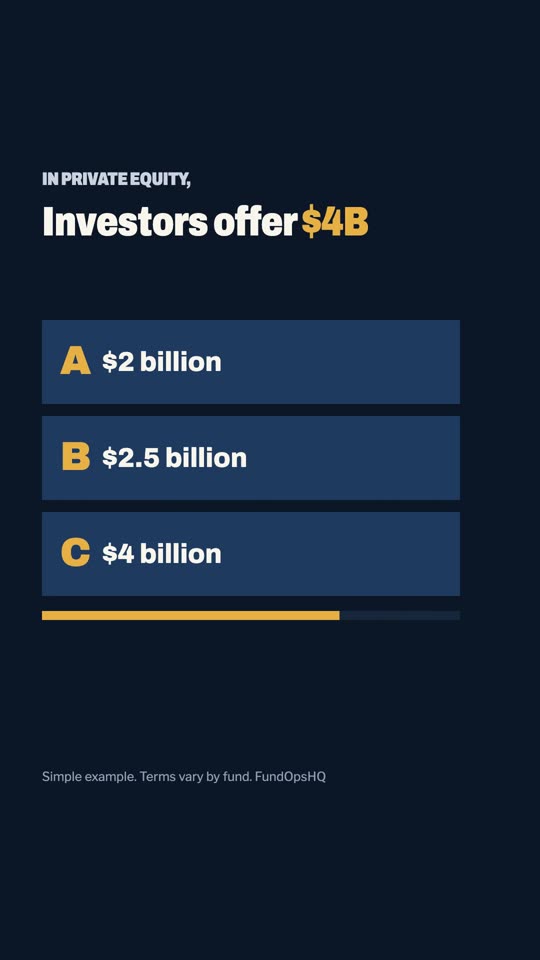 Investors offered $4B. The fund couldn't take it.21 seconds
 The same deal, with no carry23 seconds
 Part of the price only shows up later26 seconds
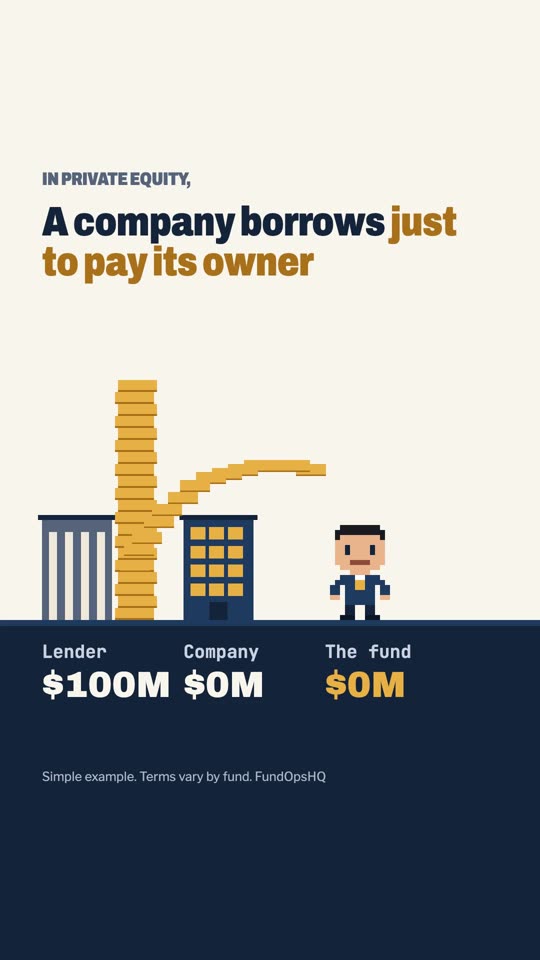 A company borrows money just to pay its owner26 seconds
 A fund can invest more than it raised26 seconds
 A fund owes you money. It sends you this instead.22 seconds
 The manager's own money in the fund18 seconds
 How a listed company disappears from the market25 seconds
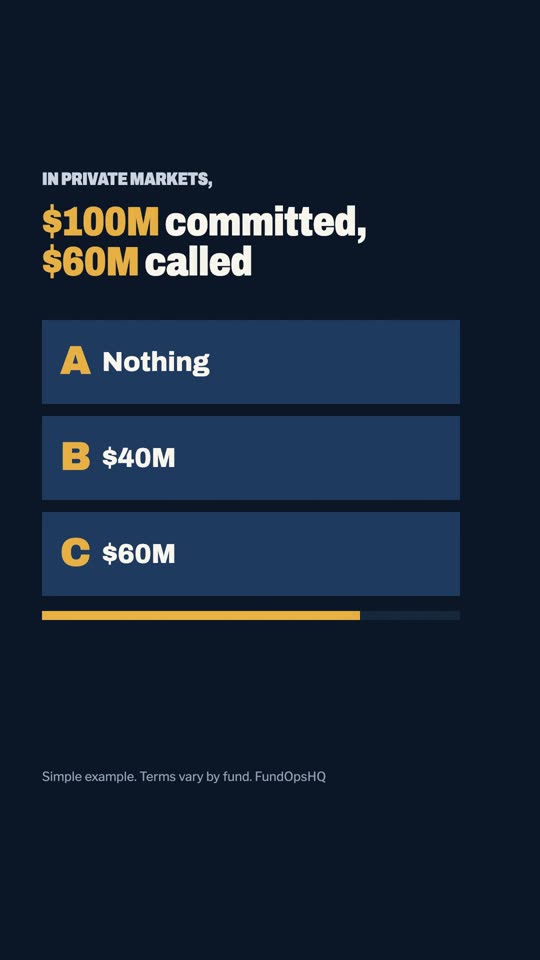 You committed $100M. $60M is in. What do you still owe?22 seconds
Private credit
 Every payment on time, and still in default36 seconds
 A company goes under. Who gets paid is a queue.39 seconds
 Lend $98. Get back $100.31 seconds
 The loan that pays its interest with more loan40 seconds
 Own loans to private companies through a share28 seconds
 A company borrows from a fund, not a bank27 seconds
 A loan's interest rate can change every quarter28 seconds
 Two lenders, same collateral. One gets paid first.36 seconds
 A default isn't the loss. What comes back is.32 seconds
 A loan repaid by ten thousand strangers34 seconds
 Most big loans now come without an early warning39 seconds
 Paying a loan back early can cost extra31 seconds
 A buyout can line up money for deals it has not found yet33 seconds
 A loan coming due can simply get more time36 seconds
 One ratio shows whether a borrower can keep up35 seconds
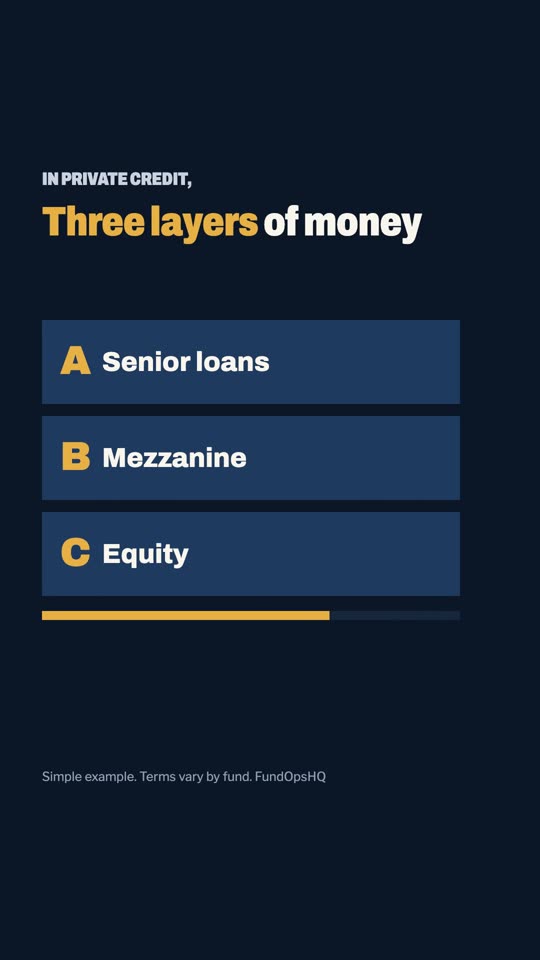 Who gets paid back second?23 seconds
 Hundreds of loans, sold off in slices20 seconds
Venture capital
 One bet can pay for all the others32 seconds
 A startup sells for $10M. The founders get nothing.34 seconds
 You can invest today and get no shares33 seconds
 Millions in the bank, and months from empty36 seconds
 The price halves. One investor ends up with twice the shares.41 seconds
 A loan to a startup that wants to become shares30 seconds
 An early check can buy shares at half the next price29 seconds
 An early investor can keep its slice, if it pays up32 seconds
 Shares for future hires can come out of the founders’ slice37 seconds
 Some investors get paid twice from the same sale35 seconds
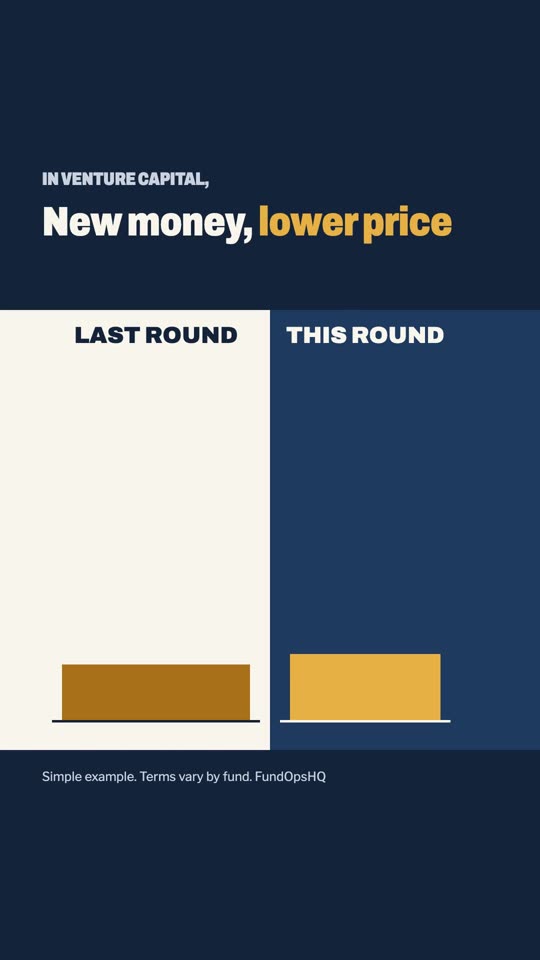 When a startup raises money and its value falls21 seconds
Real estate
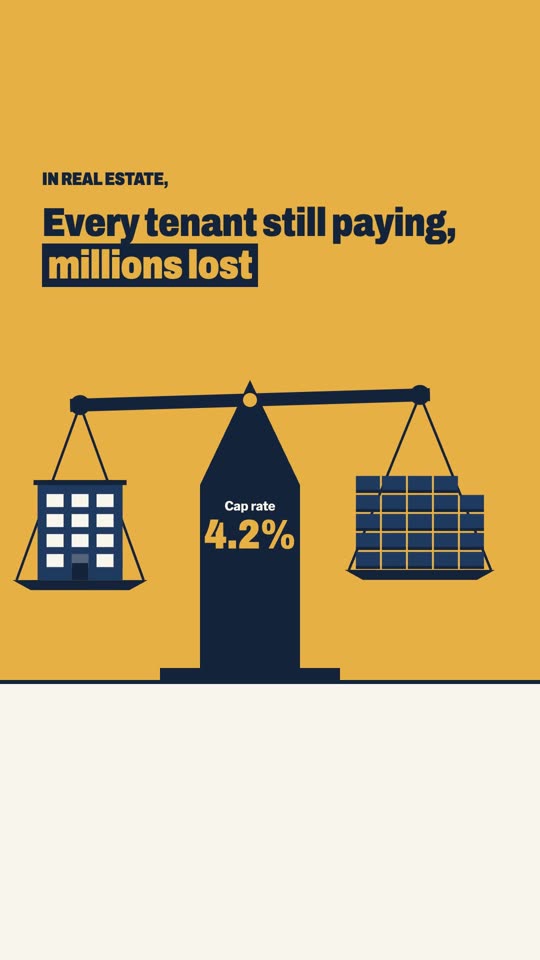 How a building loses $5M with every tenant still paying41 seconds
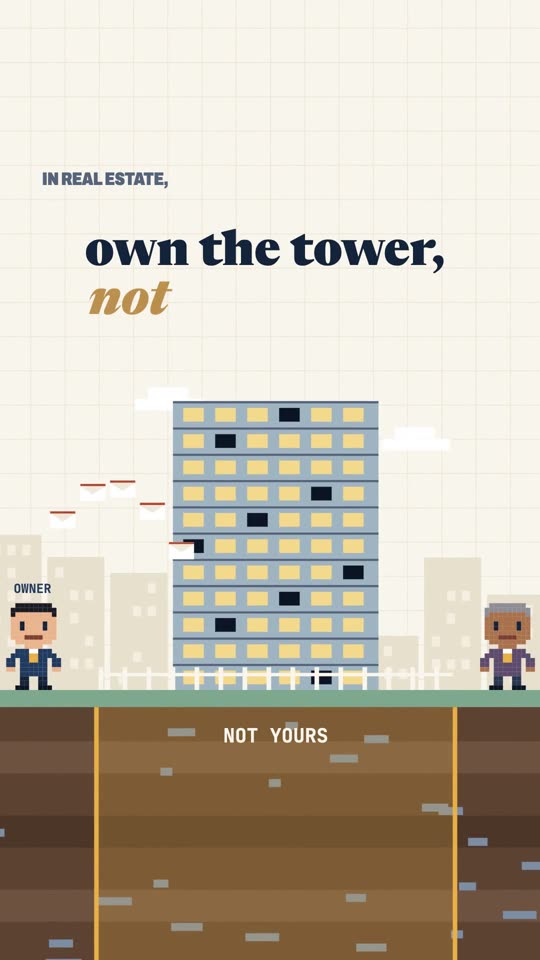 You can own the tower, and not the ground under it33 seconds
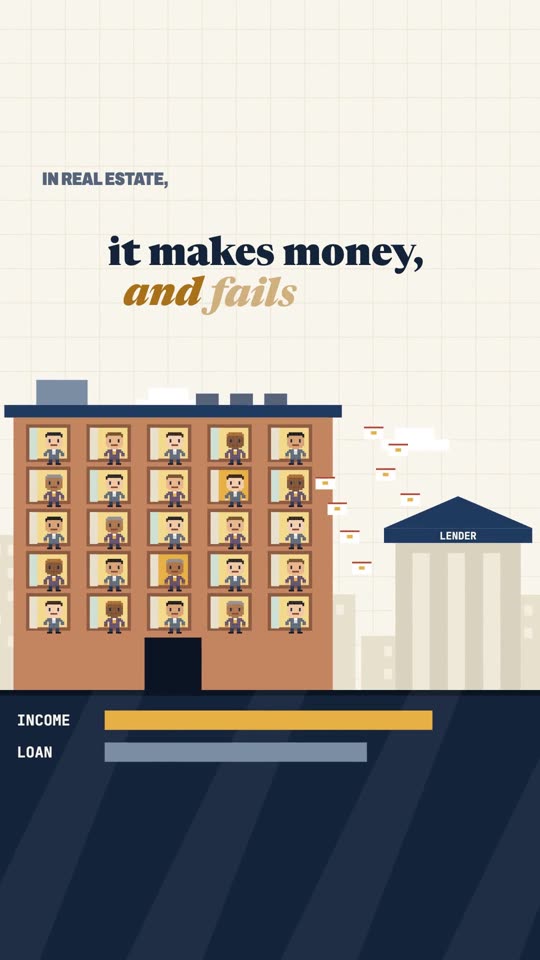 The building makes money. It can still fail the test.31 seconds
 The building loses a fifth. The owner loses half.33 seconds
 The tenant pays the building’s bills. Then what are you buying?39 seconds
 Own a slice of a hundred buildings, sell it the same day32 seconds
 A fund that buys you out, one slice a quarter33 seconds
 Every building’s price starts with one number41 seconds
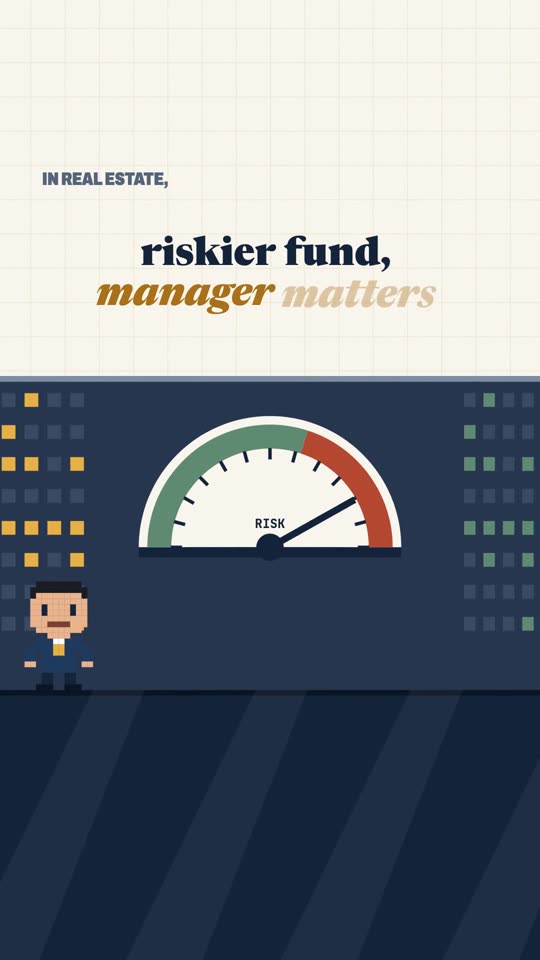 The riskier the property fund, the more the manager matters40 seconds
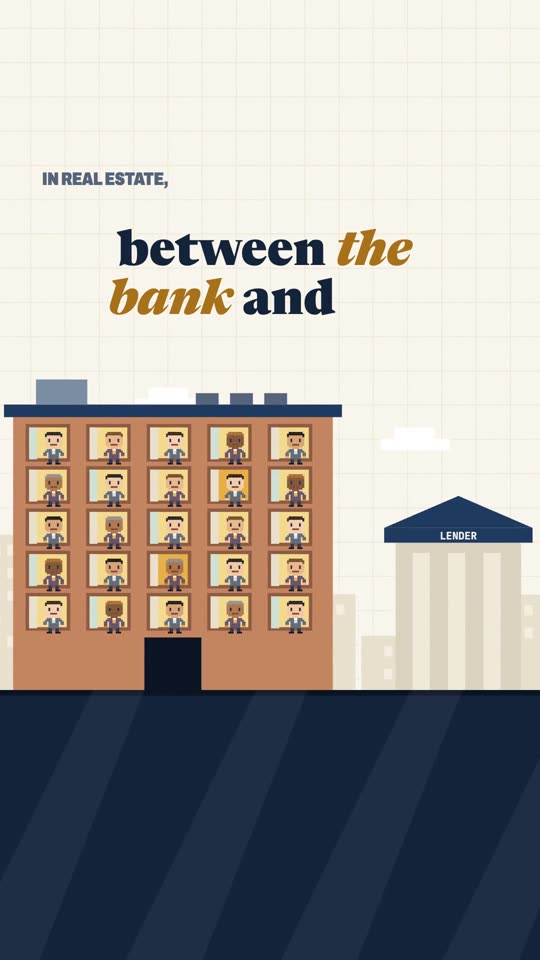 Some investors sit between the bank and the owner31 seconds
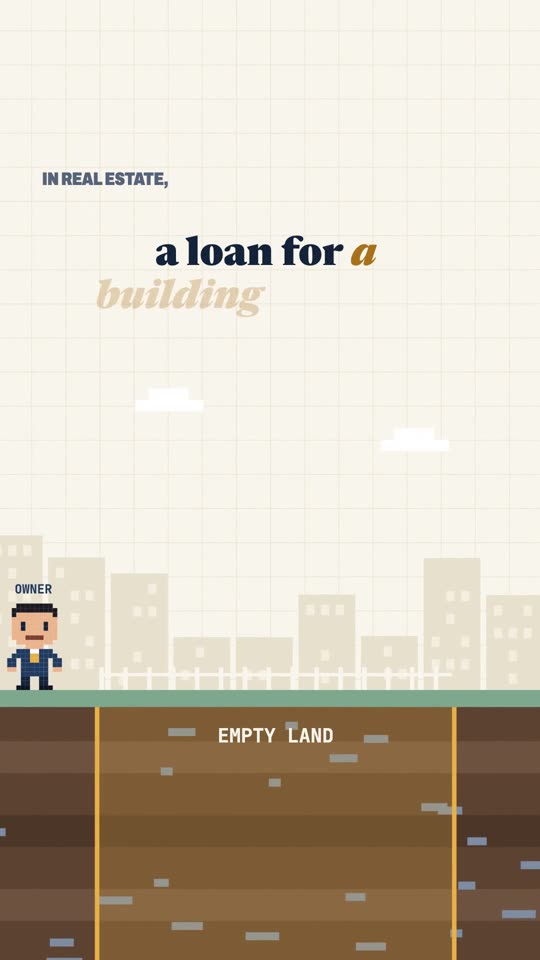 A lender can size a loan for a building that does not exist yet36 seconds
 The sponsor can earn far more than its share of the money33 seconds
 A lender can size a loan without asking what the building is worth25 seconds
Infrastructure
 Your gym membership explains how power plants get paid42 seconds
 You can run a road for decades and never own it30 seconds
 Some deals begin with an empty field33 seconds
 The road empties out. The money doesn’t.36 seconds
 A wind farm can sell years of power before it spins31 seconds
 A bridge can borrow money only the bridge has to repay34 seconds
 A regulator decides what this business can earn34 seconds
 Some infrastructure gets a raise written into the contract35 seconds
 A project can sell its output before it is built38 seconds
 Some investors would rather buy the road than build it32 seconds
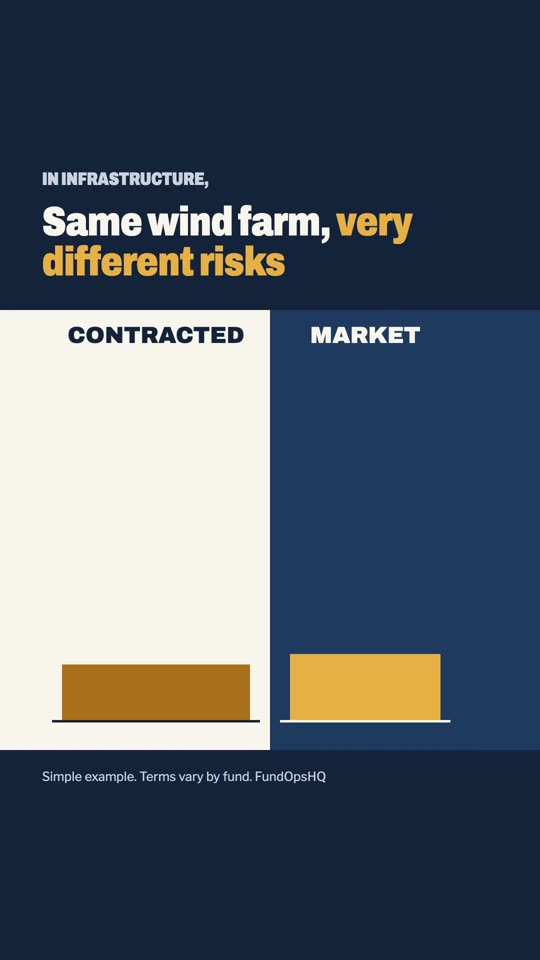 Same wind farm, same wind. One knows what it will earn.30 seconds
Hedge funds
 Everyone asked for their money back. The fund shut the door.42 seconds
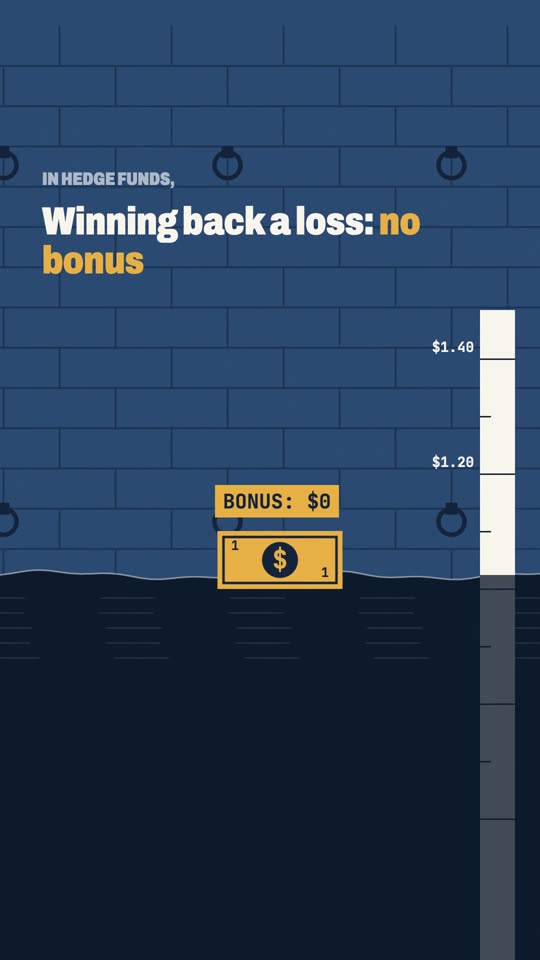 Why winning back a loss can earn a hedge fund manager no bonus41 seconds
 Bet against a stock, and you can be forced to buy it35 seconds
 Lose half. Now you need to double it.31 seconds
 You can be right about a stock, and still be forced out40 seconds
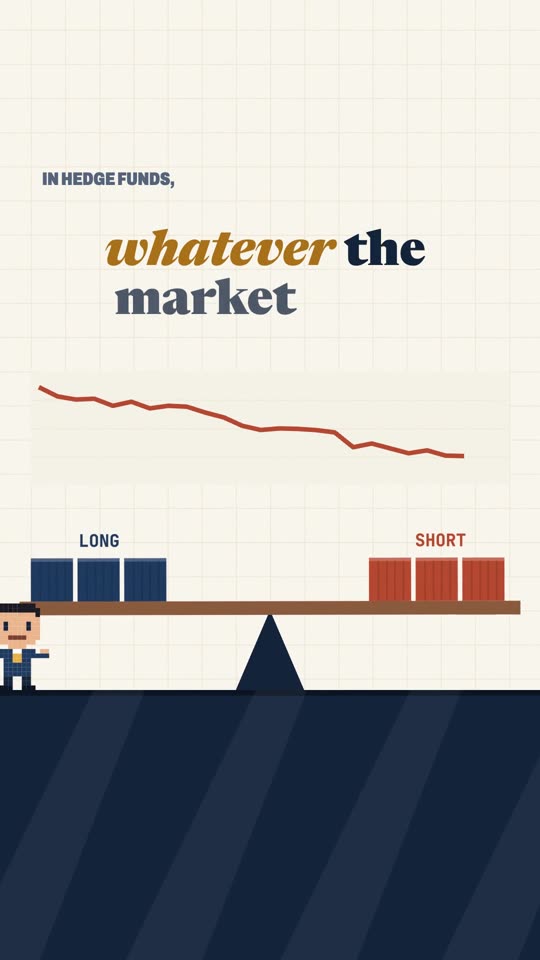 The market falls 10%. This fund does not care.36 seconds
 Two funds return the same. One is twice as bumpy.35 seconds
 A hedge fund's borrowing, shorting and trading can all run through one bank33 seconds
 A 13% year can be mostly the market31 seconds
 A fund can make money when a stock falls34 seconds
 One hedge fund can hold dozens of separate trading teams35 seconds
 Your money can leave. Part of it stays behind.18 seconds
 The stretch when a hedge fund will not give your money back21 seconds
Secondaries
 You can sell your stake in a fund before it ends33 seconds
 Ninety million, half of it later. That is not ninety.34 seconds
 One offer to every holder. Each decides alone.30 seconds
 A fund can sell a slice of every company it owns35 seconds
 Buying into an old fund can come with a string attached32 seconds
 When a manager sells to itself, someone else checks the price45 seconds
 A fund can outlive its own deadline27 seconds
Simple examples with round numbers, not advice. Terms vary by fund.
See an error?